Reviewed by Anthony Howe, Licensed Insurance Agent, NPN #20649362. Updated October 23, 2026.
What this article covers: After a career where the district handled your health coverage, retirement puts several decisions in your hands at once. This guide walks through them in the order most California educators meet them: covering the years before 65 (including Covered California), whether you qualify for premium-free Medicare Part A, what happens to your district coverage, how CalSTRS and CalPERS fit in, what to do about life insurance when the group plan ends, and how annuities are sometimes used alongside a pension. It ends with a checklist for the months before your last day.
In this article
- Why teachers have a different path
- Retiring before 65: covering the bridge years
- Do you qualify for premium-free Part A?
- What happens to your district coverage at 65
- CalSTRS and CalPERS: who handles what
- Timing your Medicare enrollment
- Life insurance after the district plan ends
- Annuities and your 403(b) or 457
- The Social Security change for teachers
- Checklist: before your last day
- Common questions
- Sources
Why teachers have a different path
We work with a lot of retiring teachers, and the same thing comes up in nearly every first conversation: for 25 or 30 years, health coverage was something the district took care of. Retirement is often the first time you’ve had to choose a plan on your own, and it tends to arrive alongside pension paperwork, a last semester and a long list of deadlines.
California educators also have a wrinkle most retirees don’t. Many school jobs here aren’t covered by Social Security, and some long-time teachers never paid Medicare tax on their school earnings. That can change what Medicare costs you, which is why it’s worth checking before you set a retirement date. For the state rules that apply to everyone, see Medicare in California.
Retiring before 65: covering the bridge years
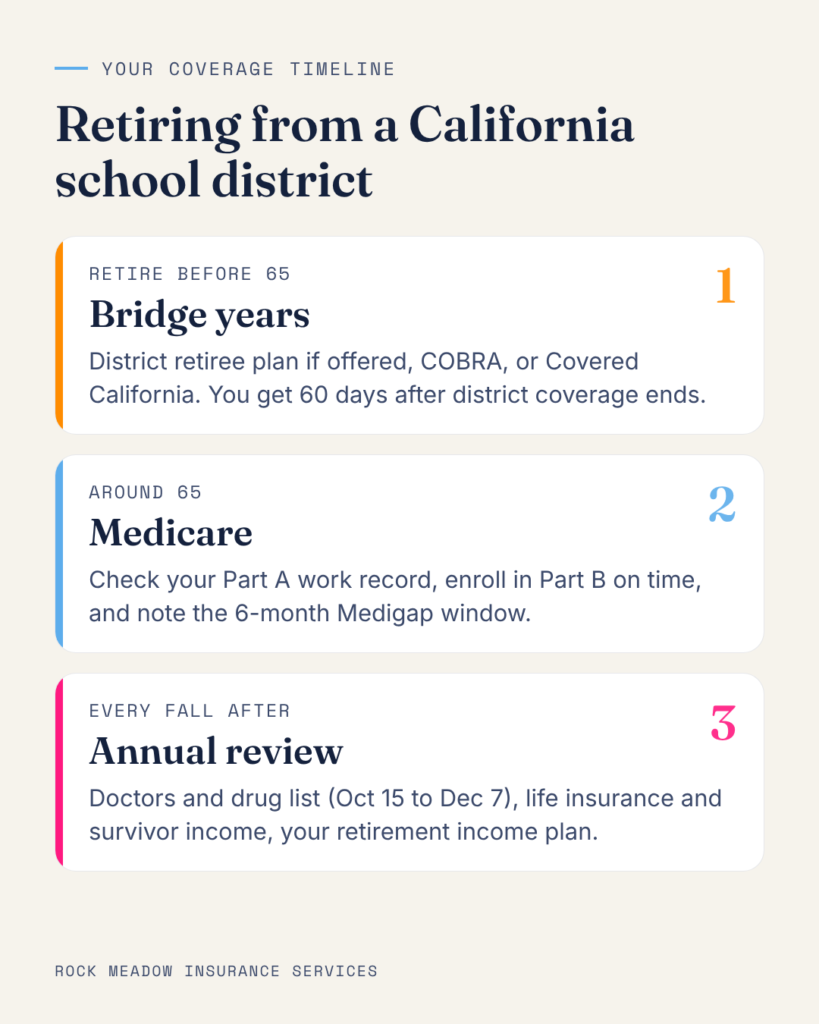
Many educators retire in their late 50s or early 60s, which leaves a gap before Medicare starts at 65. There are usually three ways to cover it:
- District retiree coverage. Some districts let retirees stay on the group plan until 65, sometimes with a contribution toward the premium. The terms vary a lot between districts and bargaining units, so ask for them in writing.
- COBRA. You can usually keep your current plan for up to 18 months, but you pay the full premium plus a small fee.
- Covered California. Losing your district coverage opens a 60-day Special Enrollment Period, so you don’t have to wait for open enrollment (November 1 to January 31).
With Covered California, premium help is based on your household income for the year, and your pension, 403(b) or 457 withdrawals and other income all count. That makes the timing of withdrawals part of your health insurance math. The enhanced federal tax credits expired at the end of 2025, so federal help is smaller for many households and may not be available at higher incomes; for 2027, California adds its own premium help for incomes up to 200% of the poverty level ($31,920 for one person). Plans are built around regional networks, so it’s worth checking your doctors by name. See Individual & Family Health in California, or the local pages for San Diego, Carlsbad and Oceanside.
Do you qualify for premium-free Part A?
Most people get Medicare Part A (hospital insurance) without a premium because they or a spouse worked about 10 years (40 quarters) in jobs that paid Medicare tax. For California school employees, the key date is April 1, 1986:
- Hired by your district on or after April 1, 1986: you’ve paid Medicare tax on your school earnings, so your teaching years count.
- Hired before April 1, 1986: you may not have paid Medicare tax on those earnings, unless you changed employers after that date or your district held a Medicare vote (a “Medicare Division”) and you chose coverage.
Even then, you may qualify through other work, such as summer jobs or an earlier career, or through your spouse’s work record. If you don’t qualify, you can buy Part A, or in some cases enroll in Part B only, and each choice affects what your district plan requires. The quickest way to know is to check your work record with Social Security through a my Social Security account or by calling 1-800-772-1213, ideally a year or more before you retire.
What happens to your district coverage at 65
Districts handle this differently. Some offer retiree coverage only until 65, some for life, and some contribute a set amount you can use toward a plan. Many that continue coverage past 65 require you to enroll in Medicare once you’re eligible and then move you to the district’s Medicare plan.
A pattern we see often: people roll straight into whatever Medicare plan the district or its carrier offers. That plan can compare well, especially when the district pays part of the premium. But a group retiree plan isn’t automatically the option that fits you best in your area, and some don’t let you back in once you leave. Before deciding either way, it’s worth asking HR:
- How long does retiree coverage last, and what does the district contribute?
- Does the plan require Medicare Parts A and B at 65?
- If I leave the retiree plan, can I ever return?
- Does the contribution continue if I choose a different Medicare plan?
- What happens to my spouse’s coverage?
CalSTRS and CalPERS: who handles what
| Teachers and certificated staff | Classified staff | |
|---|---|---|
| Pension system | CalSTRS | CalPERS |
| Where retiree health coverage comes from | Your district, not CalSTRS | Your district; if it contracts with CalPERS health, CalPERS plans |
| At 65 | Set by your district’s retiree plan | CalPERS health generally requires Parts A and B and a move to a CalPERS Medicare plan |
CalSTRS once ran a program that paid Part A premiums for some members who didn’t qualify for premium-free Part A, but it isn’t open to members who retired on or after July 1, 2012. If you’re in CalPERS health and don’t qualify for premium-free Part A, CalPERS has a form to certify that, so ask about it before 65.
Timing your Medicare enrollment
Your Initial Enrollment Period is the seven months around your 65th birthday. If you’re still working with active employer coverage, you can usually delay and use a Special Enrollment Period later. In our experience, the costly mistake isn’t signing up early; it’s signing up late without creditable coverage, because the Part B and Part D penalties last for as long as you have that coverage. Our guide for people still working at 65 covers the windows in detail.
If you’re choosing your own Medicare coverage rather than a district plan, the main fork is Medicare Advantage or Original Medicare with a Medigap plan. Your Medigap open enrollment period, six months starting when you’re 65 and in Part B, is when an insurer can’t turn you down for health reasons. See Medicare Advantage vs. Medigap in San Diego County and our look at the 2027 San Diego County plans.
Life insurance after the district plan ends
District group life insurance usually ends or shrinks when you retire. Many group policies let you convert to an individual policy without health questions, but only within a short window after coverage ends, often 31 days. Ask HR for the conversion paperwork before your last day, even if you’re not sure you’ll use it.
Your pension may also play a role. CalSTRS and CalPERS let you choose a retirement option that continues part of your monthly benefit to a spouse or other beneficiary after you die, in exchange for a lower benefit while you’re alive. Individual life insurance is another way to provide for a survivor. The two work differently, and the comparison depends on your health, your spouse’s age and other income, so it’s worth seeing the numbers side by side before your option election becomes final.
For smaller needs, such as funeral costs, final expense insurance is a permanent policy with a smaller benefit, often with only a few health questions. See Life Insurance in California, Life Insurance in San Diego and Final Expense Insurance in California.
Annuities and your 403(b) or 457
An annuity is a contract with an insurance company that can turn savings into income, now or later. Some retirees use part of a 403(b) or 457 balance to add a predictable income stream alongside their pension. The main types:
- Immediate annuities start paying income right away.
- Deferred annuities grow first and pay later.
- Fixed annuities credit a set interest rate; fixed indexed annuities credit interest based partly on a market index, within limits.
The trade-offs matter as much as the features: most deferred annuities have surrender charges if you withdraw more than an allowed amount in the early years, some have fees for optional riders, and any guarantee depends on the insurance company’s ability to pay. California gives buyers 60 and older at least 30 days to review a new annuity and return it. Moving money from a 403(b) or 457 also has tax rules, so it’s worth confirming how a rollover would be handled before you sign anything. See Annuities in California and Annuities in San Diego.
The Social Security change for teachers
The Social Security Fairness Act, signed in January 2025, repealed the Windfall Elimination Provision and the Government Pension Offset, two rules that had reduced Social Security benefits for many teachers and their spouses. If you have Social Security credits from other work, or a spouse with them, your benefit may be higher than older estimates showed. The law changed Social Security benefits, not Medicare eligibility: premium-free Part A still depends on Medicare-covered work by you or your spouse.
Checklist: before your last day
Starting six to 12 months out:
- Get your Social Security and Medicare work record.
- Get your district’s retiree benefits summary in writing.
- Ask how your group life insurance converts, and by when.
- Review your pension survivor option before you file.
- List your doctors, medical groups and prescriptions.
- If you’re retiring before 65, price Covered California and COBRA against the district plan.
- Decide how and when you’ll draw from your 403(b) or 457.
- Put every enrollment deadline on a calendar: Covered California’s 60 days, Medicare’s seven-month window, the Medigap six months.
Common questions
I never paid into Social Security. Can I still get Medicare?
Usually, yes. Medicare eligibility depends on Medicare tax, not Social Security tax, and most teachers hired after March 31, 1986 paid Medicare tax. If you don’t have enough Medicare-covered work yourself, you may qualify through a spouse, or you can buy Part A.
Does my district plan replace Medicare?
Usually not after 65. Many district retiree plans require you to enroll in Medicare and then work alongside it or move you to a Medicare plan. Ask your district how its plan coordinates with Medicare.
Can I get Covered California if I have a pension?
Yes. A pension doesn’t make you ineligible; it counts as income, which affects how much premium help you get. If district retiree coverage is offered to you, ask how it affects Covered California eligibility before you decline it.
What happens to my school life insurance when I retire?
Group coverage usually ends or drops to a smaller amount. Many policies allow conversion to an individual policy within about 31 days, without health questions. Ask HR for the details before you leave.
I’m already retired and on the district plan. Should I review it?
A yearly check is worth doing. Retiree plans change benefits and networks, doctors move between medical groups, and drugs leave formularies. Reviewing doesn’t mean you have to switch; it’s how you find out whether the plan still fits.
Where we help
Rock Meadow Insurance Services works with retiring educators across San Diego County and California, from our office in Oceanside. Because we handle Medicare, health, life insurance and annuities, we can look at the whole picture in one conversation, at no charge to you. Call (760) 654-6760, or see our Oceanside and San Diego pages. For free, unbiased Medicare counseling, California’s HICAP program is at 1-800-434-0222.
Sources
- CalSTRS, Medicare Premium Payment Program eligibility: the April 1, 1986 Medicare tax rule, Medicare Divisions, and the July 1, 2012 program cutoff.
- CMS, 2026 Medicare Parts A and B Premiums and Deductibles: premium-free Part A after 40 quarters of Medicare-covered work.
- CalPERS, Medicare for retirees: Parts A and B and CalPERS Medicare plans at 65.
- Covered California, Rates and Plans for 2027: the expired federal tax credits and 2027 state premium help up to 200% of the poverty level.
- California Department of Insurance, Annuities: What Seniors Need to Know: the 30-day free-look period for seniors and suitability.
- Social Security, Social Security Fairness Act: repeal of the Windfall Elimination Provision and Government Pension Offset.